
Qualify for an Investment Property Using Rental Income
Purchase or refinance a rental property without relying on personal-income calculation.
- Designed for real estate investors
- Purchase & refinance options
- Depending on the loan program, W-2s, pay stubs, or tax returns may not be required
- Quick consultation with an investment property specialist


Why Traditional Qualification May Not Work
Traditional mortgage guidelines aren’t always designed for real estate investors.
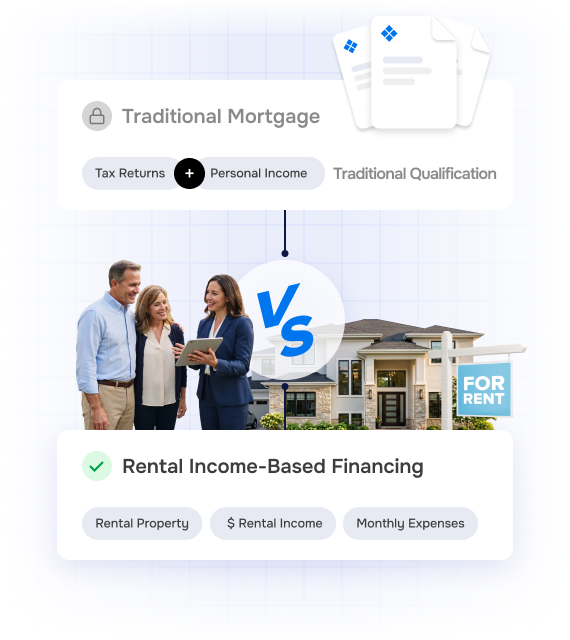
If you’re self-employed, own multiple financed properties, or take advantage of legitimate business tax deductions, your tax returns may not reflect your true financial picture. As a result, qualifying for another investment property through conventional financing can become more difficult than it should be.
Rental income-based financing offers a different approach. Instead of focusing primarily on your personal income, it evaluates whether the property’s expected rental income can support its monthly housing expenses.
If you’re building your investment portfolio, this financing solution may provide greater flexibility while helping you move forward with confidence.
Prequalification ConsultationHow Rental Income Qualification Works
Qualifying with rental income is straightforward.
Tell Us About the Property
We’ll review basic information such as the property’s location, purchase price or current value, estimated monthly rental income, and your financing goals.
We Evaluate the Property’s Rental Income
Rather than relying primarily on a traditional personal income calculation, we evaluate whether the property’s expected rental income supports its monthly housing expenses according to the applicable loan guidelines.
Review Your Financing Options
After reviewing your scenario, Drew will explain your available loan options, answer your questions, and help you determine the financing solution that best aligns with your investment strategy.
Who This Program May Be Right For
This financing option may be a good fit if you:
- Are purchasing or refinancing an investment property.
- Are self-employed or have non-traditional income.
- Own multiple financed rental properties.
- Claim significant business tax deductions.
- Prefer qualifying based primarily on rental income.
- Are looking for an alternative to conventional investment property financing.
Every investor’s situation is unique. A consultation with Drew can help determine whether this program aligns with your financing goals.
Prequalification Consultation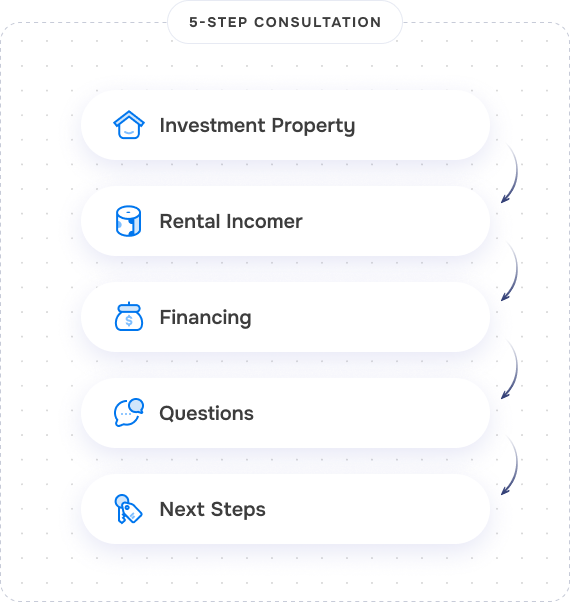
What to Expect During Your Consultation
Your consultation is an opportunity to discuss your investment goals and explore financing options tailored to your specific situation.
During your consultation, Drew will:
- Learn more about your investment property and financing objectives.
- Explain how rental income qualification works.
- Review financing options that may fit your needs.
- Answer your questions about the loan process.
- Help you understand the next steps if you decide to move forward.
Whether you’re purchasing your first rental property or expanding an established portfolio, you’ll receive personalized guidance to help you make informed financing decisions.
Prequalification Consultation
Meet Drew Ebner: Local Guidance for Real Estate Investors
Drew Ebner is committed to helping real estate investors navigate today’s financing options with confidence. He understands that every investment strategy is different and works closely with clients to identify solutions that support their long-term goals.
When you work with Drew, you can expect:
- Personalized guidance throughout the financing process.
- Clear, honest communication.
- Investment property financing expertise.
- A commitment to helping you make informed decisions.
FAQ
A DSCR (Debt Service Coverage Ratio) loan is an investment property financing option that qualifies borrowers primarily based on the property’s expected rental income rather than a traditional personal debt-to-income calculation. This approach is designed specifically for real estate investors.
Instead of focusing primarily on your personal income, lenders evaluate whether the property’s expected rental income can support its monthly housing expenses. This can make it easier for qualified investors to finance rental properties.
Depending on the loan program, traditional income documentation such as W-2s, pay stubs, or tax returns may not be required. Your loan advisor will review your situation and explain the documentation needed for your specific loan.
Yes. DSCR loans are commonly used to purchase investment properties, whether you’re buying your first rental or expanding an existing portfolio.
Absolutely. You may use a DSCR loan to refinance an existing rental property, whether you’re looking to lower your payment, access equity, or improve your financing terms.
No. Both new and experienced real estate investors may qualify, depending on the loan guidelines and the property’s financial profile.
Yes. DSCR loans are often an excellent option for self-employed investors whose tax returns may not fully reflect their actual cash flow.
Eligibility varies by program, but many single-family homes, condos, townhomes, and multi-unit investment properties may qualify. Your mortgage advisor can help determine whether your property meets the program requirements.
Some DSCR loan programs allow eligible properties to be vested in an LLC or other business entity. Availability depends on the specific loan program and investor guidelines.
Minimum credit score requirements vary depending on the loan program, down payment, and overall borrower profile. Contact us to discuss your specific situation.
Down payment requirements depend on the loan program, property type, and your financial profile. We’ll review your options and help you determine the financing solution that best fits your investment goals.
Every transaction is different, but once we have the necessary information about your investment property and financing goals, we’ll guide you through the process and keep you informed every step of the way.
To begin, we’ll typically ask for basic details about the property, such as its location, estimated purchase price (or current value for a refinance), expected monthly rental income, and your financing goals.
The easiest way to find out is to complete our short property review form. We’ll evaluate your investment scenario and let you know what financing options may be available.
Ready to Discuss Your Investment Property Financing Options?
Whether you’re purchasing your next rental property or refinancing an existing investment, Drew is here to help you explore financing solutions tailored to your goals.
Schedule a one-on-one consultation to review your property, discuss your financing options, and get expert guidance on your next investment.